Intel (INTC -28.58%) The third quarter earnings report sparked a bloodbath in the semiconductor sector. The chip giant had its worst day since 1974, plunging 29% and trailing the VanEck Semiconductor ETF down 7%.
Intel’s third-quarter results were strong, with revenue up 21% to $16.5 billion, and adjusted earnings per share more than doubling from $0.23 to $0.52, showing its turnaround efforts are paying off.
However, Intel’s fourth-quarter guidance scared away investors, calling for a sequential decline in revenue and a 600-point decline in gross margins due to a slowdown in the PC market triggered by memory shortages. While Intel’s data center and foundry businesses are growing rapidly, its client computing business, which is primarily comprised of PCs, remains its largest segment in terms of revenue. The company expects revenue of between $15 billion and $16 billion, well below the consensus of $17.1 billion, and adjusted earnings per share of just $0.25, compared to $0.44 expected.
Image source: Getty Images.
Why Intel’s peers also fell
Intel shares have soared over the past year, in part because confidence has grown in its turnaround strategy and foundry business, but also because demand for processors is expected to rise due to agentic AI, which includes products like The meta Muse personal AI agent.
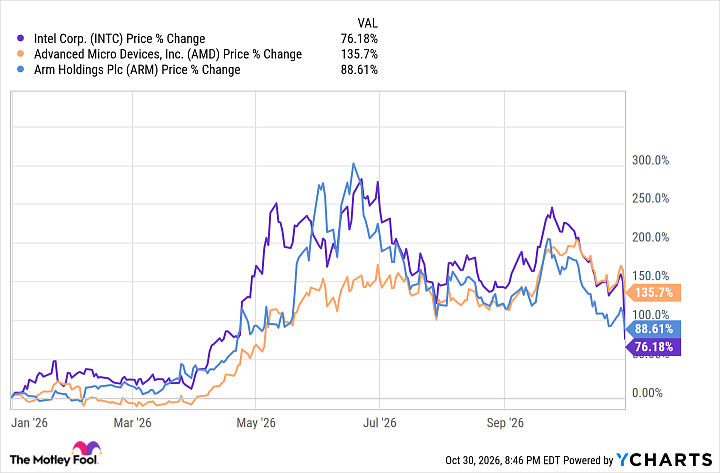
With Intel, AMD (AMD -10.88%) And Arm (ARM -9.97%) also have significant exposure to the exposure market, and all three of these stocks are up sharply this year, as the chart below shows.
INTC data by YCharts
You can also see that AMD and Arm both fell sharply in sympathy with Intel, with AMD losing 11% and Arm finishing down 10%.
However, the selloff in these two stocks has as much to do with investor sentiment as it does with the implications of Intel’s report.
AMD and Arm don’t have as much exposure to PCs as Intel and also don’t have their own foundries, meaning they aren’t exposed to the capital expenditures and risks that come with it.
AMD did not report third-quarter results, but in the second quarter, data center revenue accounted for $6.7 billion of $11.5 billion of its revenue, while $3.1 billion came from the client segment. PC weakness will also impact AMD, but not to the same extent as with Intel. AMD also saw 107% growth in the data center segment in the second quarter, and there is a good chance that this growth will accelerate in the third quarter, given the massive capex spending by hyperscalers.
Arm, whose CPU architecture differs from the x86 used by Intel and AMD, has limited exposure to the PC market but has a dominant market share in smartphones, which are experiencing the same challenges with rising memory prices.
Arm doesn’t break out its revenue by segment like its peers do, but it said data center royalties doubled year over year in its most recent quarter, indicating it’s growing just as strongly as AMD in that category.
Should you buy the dip on AMD and Arm?
AMD and Arm have soared this year on AI expectations. So as AI’s rally fades, it makes sense that these stocks will pull back as well. Although a double-digit selloff coupled with Intel’s weak earnings seems extreme, shares have moved on sentiment for much of the year.
Arm launched its new AGI processor, claiming agentic AI, while AMD is finally seen as a winner in the data center boom as it has signed contracts with several of the biggest hyperscalers. Both stocks benefited from the growing potential of processors in agentic AI.
This potential is still present, but high expectations are already embedded in these actions. We’ll know more when these stocks report earnings next week, but given the tough earnings season for AI stocks so far, investors may want to wait until sentiment stabilizes before buying these CPU stocks.
Gn bussni