A record cyberattack targeting the world’s largest cryptocurrency exchange shook the digital assets industry on Friday, dealing another blow to an industry already struggling for mainstream adoption.
Exchange Binance announced Thursday evening that more than $6 billion appeared to have flowed through wallets linked to a security breach, the highest amount ever associated with a crypto cyberattack. About $3 billion of that sum was potentially located and frozen on multiple exchanges, although it was not immediately clear whether those funds were recoverable.
It was not immediately clear whether the hackers were able to access the accounts or assets of individual customers. Binance co-CEO Richard Teng released a video statement on Friday morning aimed at reassuring users of the platform that only Binance company holdings were being targeted.
“Your assets are safe,” he said, adding that the platform had pre-existing reserves totaling more than $1 billion intended to cover customer losses, and was setting aside another $6 billion on its $167 billion balance sheet to shore up further losses.
“Binance will absorb the financial impact of these stolen funds, not our users,” Teng said in an article on Friday evening.
US officials said they were working with Binance to investigate the hack.
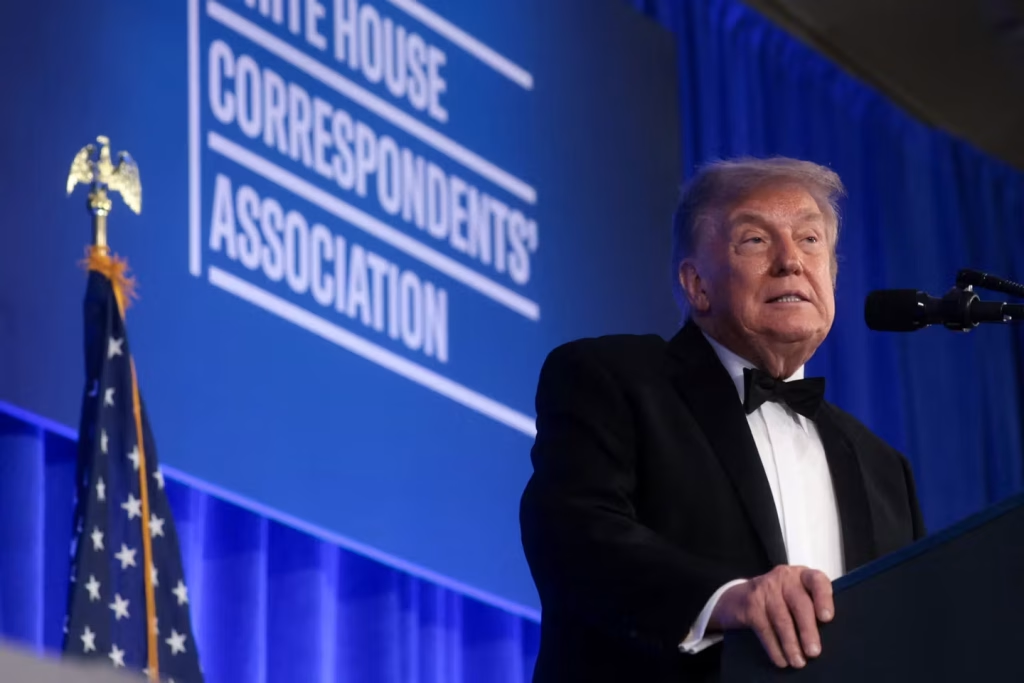
President Donald Trump said his administration was “looking into” the incident, telling reporters Friday that he was reassured by Binance’s commitment to repay any losses.
The Secret Service said it was working with private sector partners to identify, freeze, trace and recover funds stolen from Binance, but that the investigation was still in its early stages.
The hack is the latest setback for crypto, which continues to have a reputation for being too volatile – and too vulnerable to criminal activity – for widespread use. The scale of the hack echoes the collapse of crypto exchange FTX, which, while not the result of a cyberattack, resulted in billions in losses.
The renewed doubts were reflected in the value of Bitcoin, which fell as much as 5% to below $76,000, accelerating a month-long slowdown. Other affected cryptocurrencies fell as much as 9%.
The crypto industry was already recovering from Congress’ failure over the Clarity Act, a bill that would have granted full legal protection to crypto assets in the United States.
Despite bipartisan support for key elements of the legislation, its passage was torpedoed by a battle over conflict of interest rules for elected officials, including President Donald Trump.
The president revealed in documents that he made more than $1 billion from crypto last year.
The Binance hack risks prolonging that reckoning, experts said.
“It will be imperative for Binance to cover losses not only to its own reputation and value, but I expect there to be some level of cooperation within the space as they consider the collective reputational harm that this may, rightly or wrongly, cause to the industry,” Laura Clatworthy, head of digital assets at law firm Edwin Coe, said in a statement.
This cooperation was evident in the immediate responses of other major crypto players. Tether and Circle, which operate the world’s two largest stablecoins, both worked quickly to freeze assets involved in the hack.
Trump-backed crypto platform World Liberty Financial also worked to freeze USD1 and WLFI holdings linked to the attackers, a spokesperson told NBC News.
Most USD1 and WLFI transactions take place on Binance, according to blockchain data.
More than $27 million (US$1) was involved in the attack, analytics group TRM Labs reported. The group also estimated that $2.4 billion in Bitcoin and Ethereum will never be recovered.
The origins of the hack remain obscure. The entire heist happened in just 20 minutes starting around 4 p.m. ET on Thursday.
Binance initially said the attack involved a compromised laptop, but a subsequent investigation revealed “additional breach points.”
Several blockchain analysis firms said the hack had attributes associated with previous operations believed to have been carried out by North Korean actors.
Teng, co-CEO of Binance, said Binance’s investigation has not yet identified the attackers.
At least one prominent tech CEO couldn’t help but make light of the situation. Elon Musk left a “yeah” emoji in response to an X user who noted that collapsed crypto exchange FTX had initially also told users their funds were safe amid a wave of losses.
Binance co-founder CZ Zhao responded: “Elon, I have a lot of respect for you, but now is not the time to troll. Please stop.”
Zhao noted that his SpaceX shares – the proceeds of a $500 million Binance-related investment in Twitter, were now worth more than $1 billion.
“I would appreciate it if you would show some support. Thank you!”
Gn headline