Artificial intelligence (AI) infrastructure stocks have been under pressure lately as investors worry about high financing costs and the growing debt that many infrastructure companies are taking on to finance data center construction.
This explains why fast-growing companies like Applied digital (APLD -8.22%) have declined considerably in recent months. The company, which designs, builds and operates data centers to manage AI workloads and high-performance computing (HPC) applications, lost 27% of its value in three months.
Wall Street, however, seems confident about Applied Digital’s prospects for the coming year. Let’s see why this is the case and check if this AI stock can live up to expectations.
Image source: Getty Images.
Applied Digital is a major beneficiary of the AI infrastructure boom
The demand for AI data centers is growing at a breakneck pace. Semiconductor research and consulting provider SemiAnalysis forecasts that 25 gigawatts (GW) of net data center capacity will be added in 2026, significantly more than last year’s 15.6 GW. Better yet, data center capacity additions are expected to accelerate in 2027 to reach 51.2 GW.
APLD Applied digital
$17.82-$1.60 (-8.22%)
NASDAQ · At 4 p.m. ET on 10/30/26
Applied Digital builds and leases AI factories and data centers, which explains its growth at an incredible rate. The company’s revenue in the first quarter of fiscal 2027 (which ended Aug. 31) jumped 322% year over year to $342 million. This impressive acceleration is attributable to the delivery of 75 megawatts (MW) of data center capacity on July 1.
Notably, Applied Digital delivered an additional 75 MW of capacity after the end of the quarter. It now has a total active capacity of 250 MW at its Polaris Forge 1 data center complex. Looking ahead, management plans to bring 600 MW of data center capacity online over the next 12 months. This suggests a significant increase in Applied Digital’s top line as it will see a significant increase in rental revenue.
Better yet, Applied Digital plans to operate a total data center capacity of between 3.5 gigawatts (GW) and 4 GW by the end of 2030. This significant expansion over the next four years will drive Applied Digital’s growth. It’s worth noting that the company already has $36 billion in contract rental revenue across its five data center campuses. These rental contracts have a base duration of 15 years.
Importantly, Applied Digital management highlighted earlier this year that its contract rental revenue could reach $86 billion if customers exercise all renewal options. This revenue pipeline is based on contracts for 1.41 GW of capacity already in place. Thus, Applied Digital’s potential capacity expansion by 2030 could pave the way for further growth in its revenue portfolio.
Unsurprisingly, analysts expect Applied Digital’s revenue to increase more than threefold in just two fiscal years.
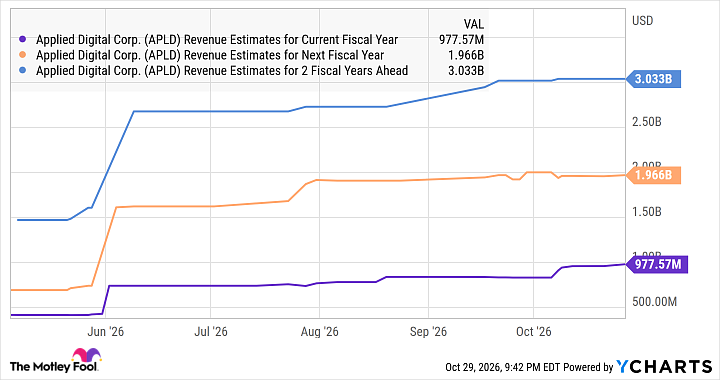
APLD revenue estimates for current fiscal year data by YCharts
But what about the debt?
Applied Digital reported debt of $6.4 billion in the fiscal first quarter. That’s significantly more than last year’s debt of $687 million. Unsurprisingly, Applied Digital’s interest expense jumped 866% year over year to $77.4 million.
However, investors should note that more than 80% of Applied Digital’s debt will mature in fiscal 2031 or later. We’ve already seen that the company’s revenue growth is poised to accelerate through fiscal 2029, and the trend will continue beyond that period as it adds capacity. Applied Digital should therefore be able to repay its debt in the long term.
Applied Digital also emphasizes that the majority of its capacity will be online in 2028, reaching 1.51 GW after a few years. Additionally, Applied Digital estimates that the net operating margin of its five existing data center campuses will be greater than 80%. As a result, the company should be able to generate enough profit from 2029 onwards to cover interest costs and repay debt.
So it’s easy to see why analysts remain bullish on this AI infrastructure stock’s prospects for the year ahead. Applied Digital has a 12-month median price target of $69, implying a 255% jump from current levels. Additionally, 18 of 20 analysts covering the stock rate it a Buy. Applied Digital’s recent decline has brought its price-to-sales ratio down to just 6.5.
That’s pretty cheap for a company that’s growing revenue at an impressive rate and has the potential to maintain momentum over the long term. If Applied Digital’s revenue climbs to $3.03 billion in fiscal 2029 and it continues to trade at 6.5 times sales, its market cap will reach $19.7 billion. That’s more than triple its current market capitalization.
Wall Street’s price target is even more ambitious. However, the discussion above suggests that this growth stock could become a multi-bagger stock over the next three years, so investors should consider using its pullback as a buying opportunity.
Gn bussni