Want to bookmark your favorite articles and stories to read or view later? Start your independent membership today.
Join us today
Already a member? Log in
Google’s stock price has fallen dramatically amid panic around AI.
Parent company Alphabet ended Thursday down more than 12 percent, wiping $500 billion from its value. It’s the biggest crash ever in Google’s history, and the second largest among U.S.-listed companies following a $593 billion plunge in Nvidia’s value last year after the rise of Chinese company DeepSeek AI sparked fears that U.S. artificial intelligence companies could lose the race.
This comes after Alphabet’s latest results showed disappointing results in its search advertising business and the scale of its vast spending on artificial intelligence. But shareholders fear these huge bets won’t come true and the company and the rest of the tech industry won’t recoup their investment in AI.
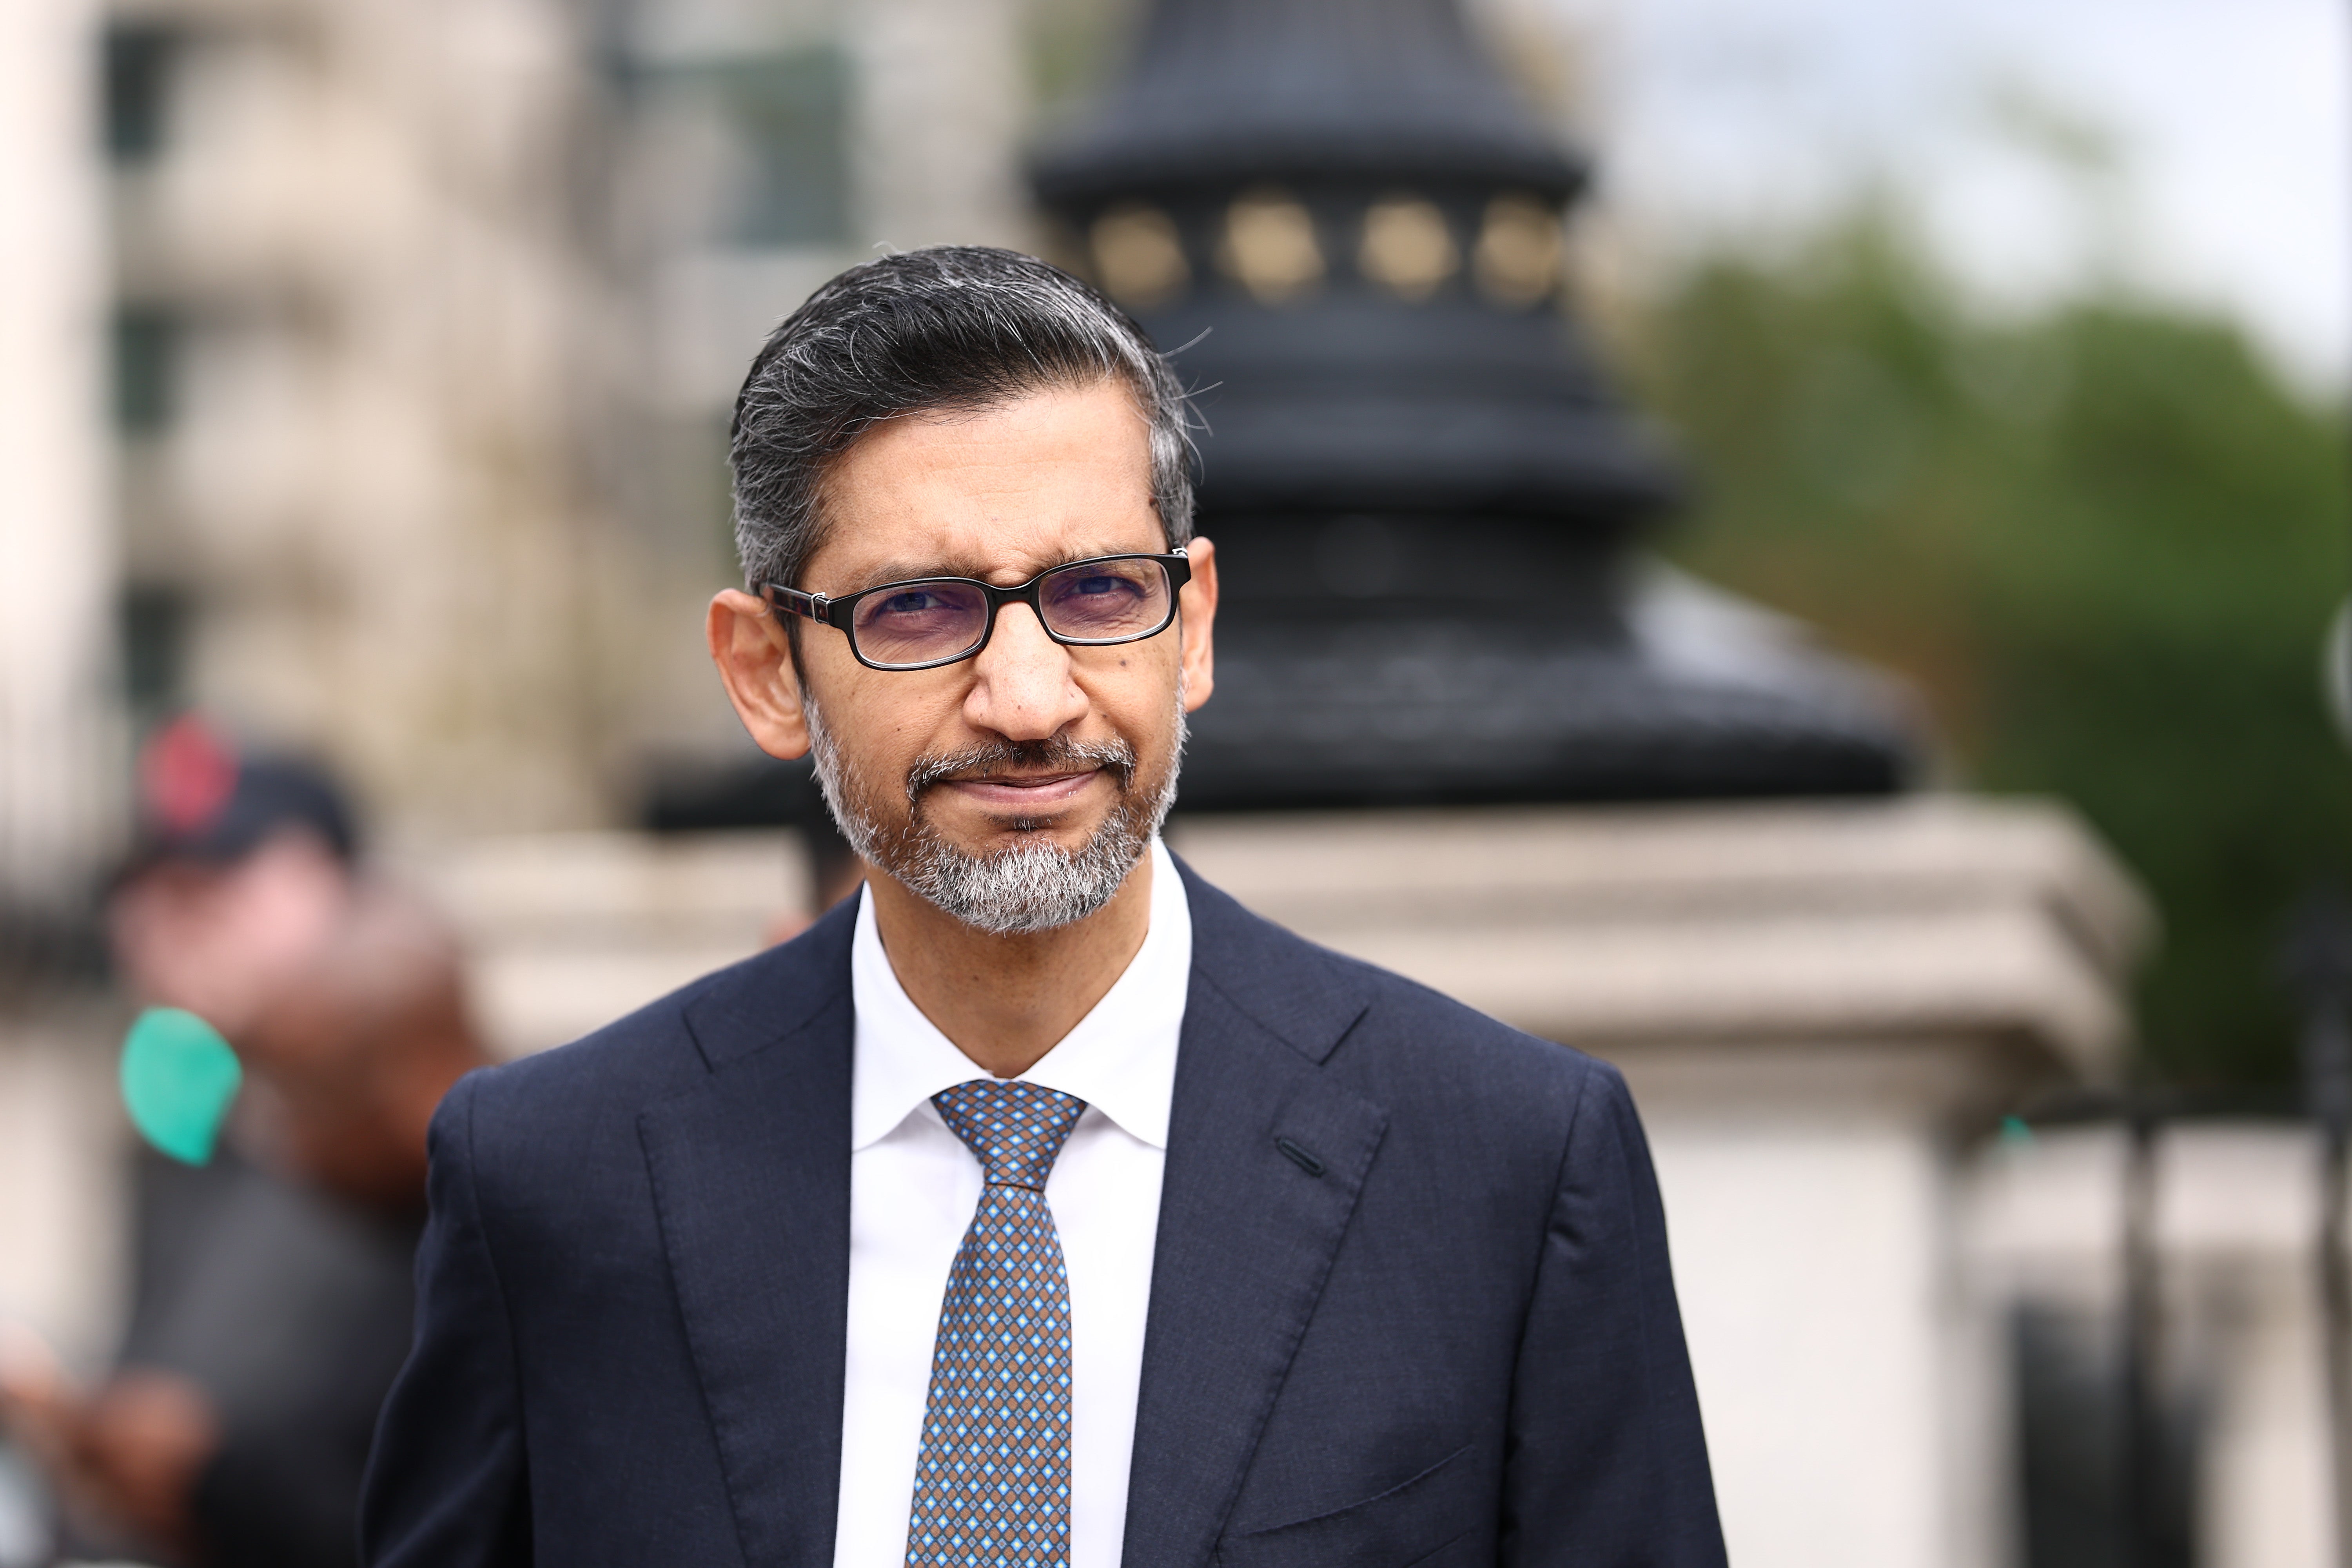
The results showed that Google is already benefiting from the AI boom, with revenue from its cloud business more than doubling. But investors worry that in the search business that still accounts for a large portion of its profits, Google has yet to see its adoption of AI results turn into profit.
Google and its CEO Sundar Pichai have sought to aggressively adopt AI, after a relatively slow start against other companies such as OpenAI. It began using its Gemini model to answer many search queries, for example, despite the fact that advertising in search results is a huge and reliable business for parent company Alphabet.
“In a market worried about AI cannibalizing the franchise, investors need to see research accelerate, not decelerate,” said Dave Wagner, portfolio manager at Aptus Capital Advisors.
“The cloud is spreading the story, but until research shows that AI is additive, the stock will likely decline.”
The Mountain View, Calif., company reported negative free cash flow of $9.1 billion, when analysts expected it to be close to break-even.
Aggressive efforts to expand cloud capacity and fund AI development led Alphabet to spend $5.9 billion last quarter, the first time it went into the negative in 22 years as a public company.
Total revenue missed Wall Street targets: Google Cloud’s revenue growth exceeded expectations, but was not enough to offset a $1.4 billion shortfall in advertising revenue.
Alphabet’s second straight quarter of negative cash flow was a sharp turning point for a company that has long been one of the tech sector’s most prolific cash generators.
Additionally, Alphabet still plans to significantly increase its capital spending for 2027, increasing from this year’s spending guidance of $195 billion to $205 billion, Chief Financial Officer Anat Ashkenazi told analysts on a conference call.
Although executives did not quantify spending for 2027, investors were nervous about a sharp increase.
“A $300 billion (capex) number could potentially spook the market because free cash flow is now ultimately negative,” said Jeremy Saltsburg, head of investments at Check Capital.
In contrast, rival Microsoft, which also reported results on Wednesday, saw its shares rise more than 5%, fueled by positive free cash flow that beat analysts’ estimates.
Ashkenazi added that she expected margin pressure in the near term due to the use of third-party cloud capabilities.
Net income available to Alphabet common shareholders fell 25% to $26.17 billion, and adjusted earnings per share of $2.67 missed Wall Street targets of $3.02.
The results reflect the enormous costs of developing AI, with investors concerned about both possible overspending and the risk of falling behind competitors by not spending enough.
Total third-quarter revenue of $127.6 billion fell short of analysts’ estimate of $128.2 billion, according to LSEG data. Advertising revenue came in at $82 billion, below expectations of $83.4 billion.
Chief Commercial Officer Philipp Schindler attributed a larger-than-expected deceleration in search advertising growth to increased use of AI Mode, a chatbot interface for the search engine that the company continues to experiment with on ads.
Google would begin rolling out AI-powered ads in international markets, Schindler said in a conference call.
Alphabet has tried to offset disappointing advertising performance by highlighting its cloud computing unit, including debuting Thomas Kurian, CEO of GoogleCloud, as a speaker on the earnings conference call.
Google Cloud revenue beat estimates and more than doubled to $30.71 billion in the third quarter ended September 30.
Kurian said sales of Google’s tensor processing units (TPUs), which compete with Nvidia’s GPU chips, had become a significant contributor to its business unit.
Alphabet began accounting for revenue from direct sales of what it calls its “TPU systems,” covering not only chips but also associated hardware and software, last quarter.
But Ashkenazi warned that stockpiling TPU would put additional pressure on free cash flow.
Google Cloud’s backlog stood at $561 billion and Alphabet expects to recognize more than 55% of that as revenue over the next 24 months, she added.
The world’s third-largest cloud services provider after Amazon Web Services and Microsoft’s Azure, Google Cloud has expanded its enterprise commitments, supported by multi-year cloud and AI infrastructure deals in cybersecurity, retail and financial services.
Alphabet, Microsoft, Amazon and Meta are collectively expected to spend more than $700 billion in 2026 to expand AI data center footprints, chips and high-performance networking capacity.
Facing supply bottlenecks of advanced silicon and data center power, Alphabet’s investments in custom tensor processing units alongside third-party GPUs have helped expand its service delivery capabilities.
Earlier on Wednesday, Google sought to preempt the results and counter the perception of losing out in the AI race by unveiling the new Gemini 4 Carbon model.
That meant the company was once again “leading at the frontier,” CEO Sundar Pichai said on the call.
Subsequently, Bernstein analysts asked in a note: “Did Google rush the rollout of the Gemini 4 models to compensate for weaker financial metrics? And are the models ready for commercial deployment?”
Gn headline