Oil prices posted their biggest decline in three months on Monday after a series of headlines on Iran gave investors hope that the Trump administration would find a way to end the conflict without further escalation.
International Brent crude oil fell 7.6% to close the day at $104.77 a barrel, while U.S. crude oil fell 7.3% to $96.46 a barrel.
These are the largest one-day percentage declines since July 27. For both major oil benchmarks, it was the biggest one-day decline in dollar terms since April 17.
Earlier on Monday, Iran’s IRNA news agency cited the Iranian president’s comments that the supreme leader had “granted the government certain authorities” to “seek to resolve issues through dialogue” with his “enemies.”
Traders read this as Iran’s choice to continue diplomatic negotiations with the United States through mediators, rather than escalating the war through further strikes against American allies in the region.
This report followed Sunday’s announcement that “Trump, for now, wants to let negotiations play out” with Iran, according to Axios.
After oil prices closed for the day, NBC News asked President Donald Trump if he planned to strike Iran after the midterms, and he twice responded, “No.”
As Trump’s response circulated online, prices continued to slide.
NBC News reported that Trump was presented with options to resume major combat operations against Iran. However, officials warned at the time that no final decision regarding the war had been made.
Energy markets are on edge after several reports last week suggested Trump could resume strikes against Iran after Tuesday’s midterm elections, which could lead to Iran again attacking energy assets scattered across the Middle East.
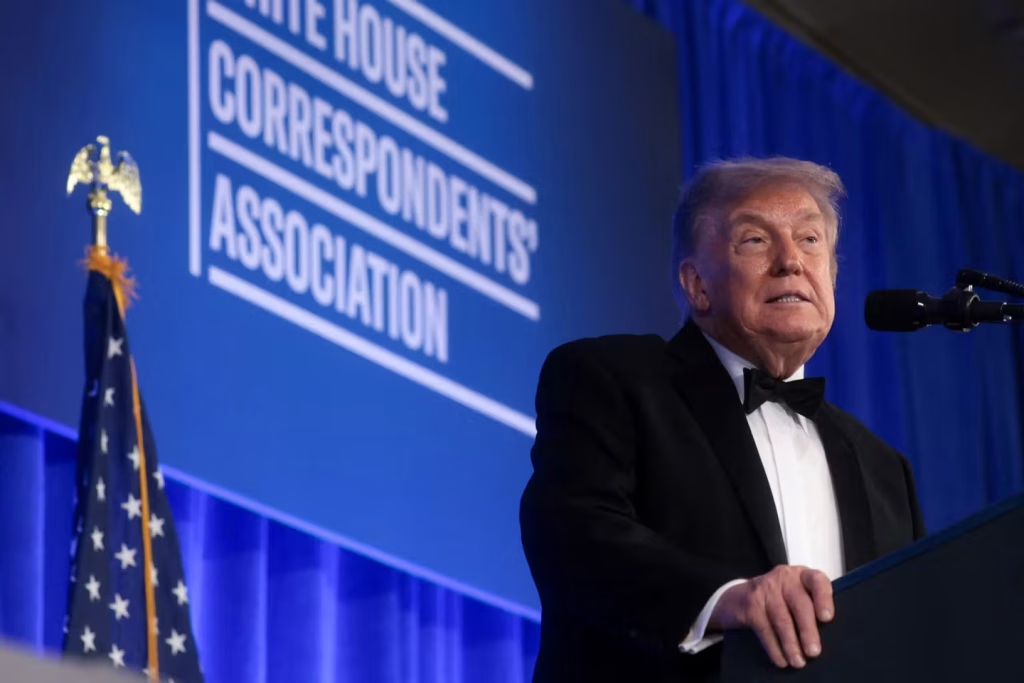
Trump took note of Monday’s drop.
“Today oil is down $10,” Trump told reporters in Washington. “And it’s going to go down further because we’re winning with Iran, winning easily.”
Trump then posted a message about it on social media, writing: “Iran wants a settlement ASAP. It could happen!”
Yet experts say global energy markets remain exposed to multiple risks.
“A broader conflict resulting in major damage to energy infrastructure could push prices up to $150” per barrel, wrote Francisco Blanch of Bank of America in September.
“If skirmishes to curb oil flows continue until the end of the year, Brent could trade in a range of $95 to $120” per barrel, he wrote.
That leaves open the possibility of a further rise in oil prices, which have been climbing all year, putting pressure on consumers around the world.
Since the start of the war in Iran in late February, global oil prices have increased by around 45%.
Another problem facing the American economy is the high price of diesel fuel.
On Monday, diesel futures fell 5.4%, their biggest one-day decline since May 6. But, like oil, this benchmark is up nearly 110% since the start of the year.
The price of diesel has risen much more dramatically this year than unleaded gasoline, as the war in Iran and the war between Ukraine and Russia have reduced supply.
Russia is historically a major exporter of diesel in the world. But the Ukrainian strikes have seriously damaged its refining capacity.
After a brief pause, Ukraine has resumed attacks on Russian diesel refineries in recent days.
Economists are particularly concerned about the unprecedented rise in diesel prices, due to the knock-on effect that rising fuel prices for transporting consumer goods can quickly have on the economy.
As of Monday morning, the average price of diesel nationwide in the United States was $6.29 per gallon, up 77% since the beginning of the year.
Gn headline