As technology companies rush to build data centers, demand for the memory chips that make artificial intelligence (AI) computing possible has skyrocketed. One of the leading manufacturers of memory chips for AI hyperscalers is Micron technology (UM +2.77%).
So far this year, Micron stock has soared 225%, making it the third best performer in the market. Nasdaq-100. Nonetheless, Micron shares have seen considerable volatility over the past two months and are trading about 24% below their all-time high.
I think this disconnect is about to be reversed. October 28 and 29, Alphabet (GOOGL +1.19%) (GOOG +0.84%) And Amazon (AMZN +1.61%) are expected to publish their quarterly results. While investors will undoubtedly focus on their AI-related capital expenditures (capex), I think another topic could emerge as a major discussion point: the global memory shortage. If my prediction is correct, Micron could start to recover just in time for Halloween.
UM Micron technology
$928.76+$25.06 (+2.77%)
NASDAQ · At 4 p.m. ET on 10/27/26
Amazon has already warned investors about rising memory costs
For most of the AI revolution, investors have primarily associated infrastructure with graphics processing units (GPUs) designed by Nvidia and application-specific integrated circuits (ASICs) designed by Broadcom. However, GPUs and custom silicon cannot operate efficiently without sufficient memory. Micron manufactures dynamic random access memory (DRAM) and high bandwidth memory (HBM), both of which are essential components of the AI chip stack.
Interestingly, Amazon CEO Andy Jassy already highlighted the growing importance of memory during the company’s latest earnings conference call. Jassy explained that Amazon plans to increase its capital budget for 2026 to $220 billion. — up from its previous forecast of $200 billion, partly due to higher memory costs.
Meanwhile, Alphabet raised its 2026 investment guidance to between $195 billion and $205 billion during its second-quarter earnings call. Management attributed the increase to accelerating infrastructure investment and capacity supply constraints. Although Alphabet did not explicitly identify memory as responsible, its comments reinforce the underlying idea that the demand for AI computing is insatiable.
As both companies prepare to report earnings this week, investors should pay close attention to any additional comments regarding memory availability, pricing and infrastructure spending.

Image source: Getty Images.
Elon Musk has also just spoken about AI memory
Amazon and Alphabet aren’t the only companies facing a memory shortage. Earlier this month, Elon Musk took to X (formerly Twitter) to discuss the bottlenecks facing AI infrastructure development. Musk specifically identified RAM supply as a constraint, supporting the idea that memory availability is becoming just as important as access to advanced processors.
This distinction is important because the AI infrastructure boom goes beyond simply acquiring as many GPUs as possible. AI models need memory to support training and inference. Training involves teaching the AI to recognize patterns, while inference occurs when those patterns are deployed to perform a real task rather than just answering a query. Both activities require significant memory, especially as applications become more complex in autonomous systems, robotics, and agentic AI.
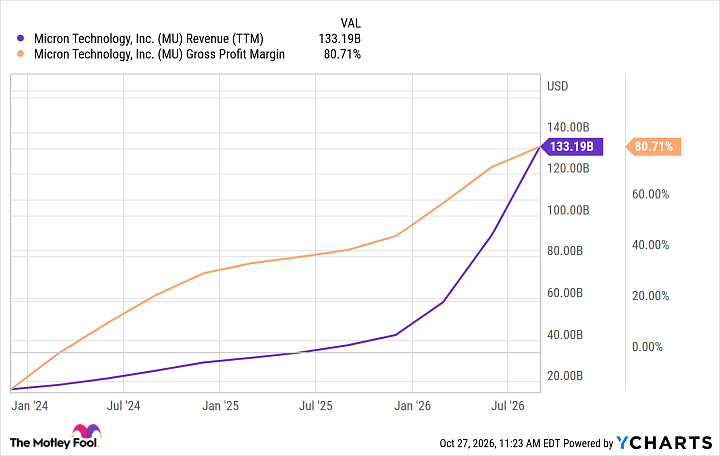
A prolonged memory shortage could create favorable conditions for Micron. When demand for a product exceeds available supply, manufacturers can charge higher prices. For Micron, this is already happening and is resulting in accelerated revenue growth, increased profit margins and earnings visibility.
MU Earnings Data (TTM) by YCharts
October 30 could be a major catalyst for Micron stock
One of the biggest headwinds weighing on Micron’s stock right now is skepticism about the semiconductor industry’s boom-and-bust cycles and whether hyperscalers can keep pace with their infrastructure spending. I think the upcoming earnings reports from Amazon and Alphabet will help answer this question.
If executives explicitly focus on memory shortages, rising component prices, or growing demand for memory-intensive AI applications, investors could begin to view Micron’s growth as more sustainable than expected.
My prediction is that earnings season will become a turning point for Micron stock. While the world’s largest AI developers point to the sector’s shortcomings, investors should recognize that Micron’s opportunity extends well beyond this year. With stocks still trading significantly below their all-time high, positive commentary could provide a much-needed catalyst for a new rally.
Gn bussni